
Prepare for retirement
A structured way to prepare: what financial freedom means to you, which paths are realistic, which uncertainties matter, and a review rhythm that keeps your finances aligned with the life you want. Not a product. A plan you run.
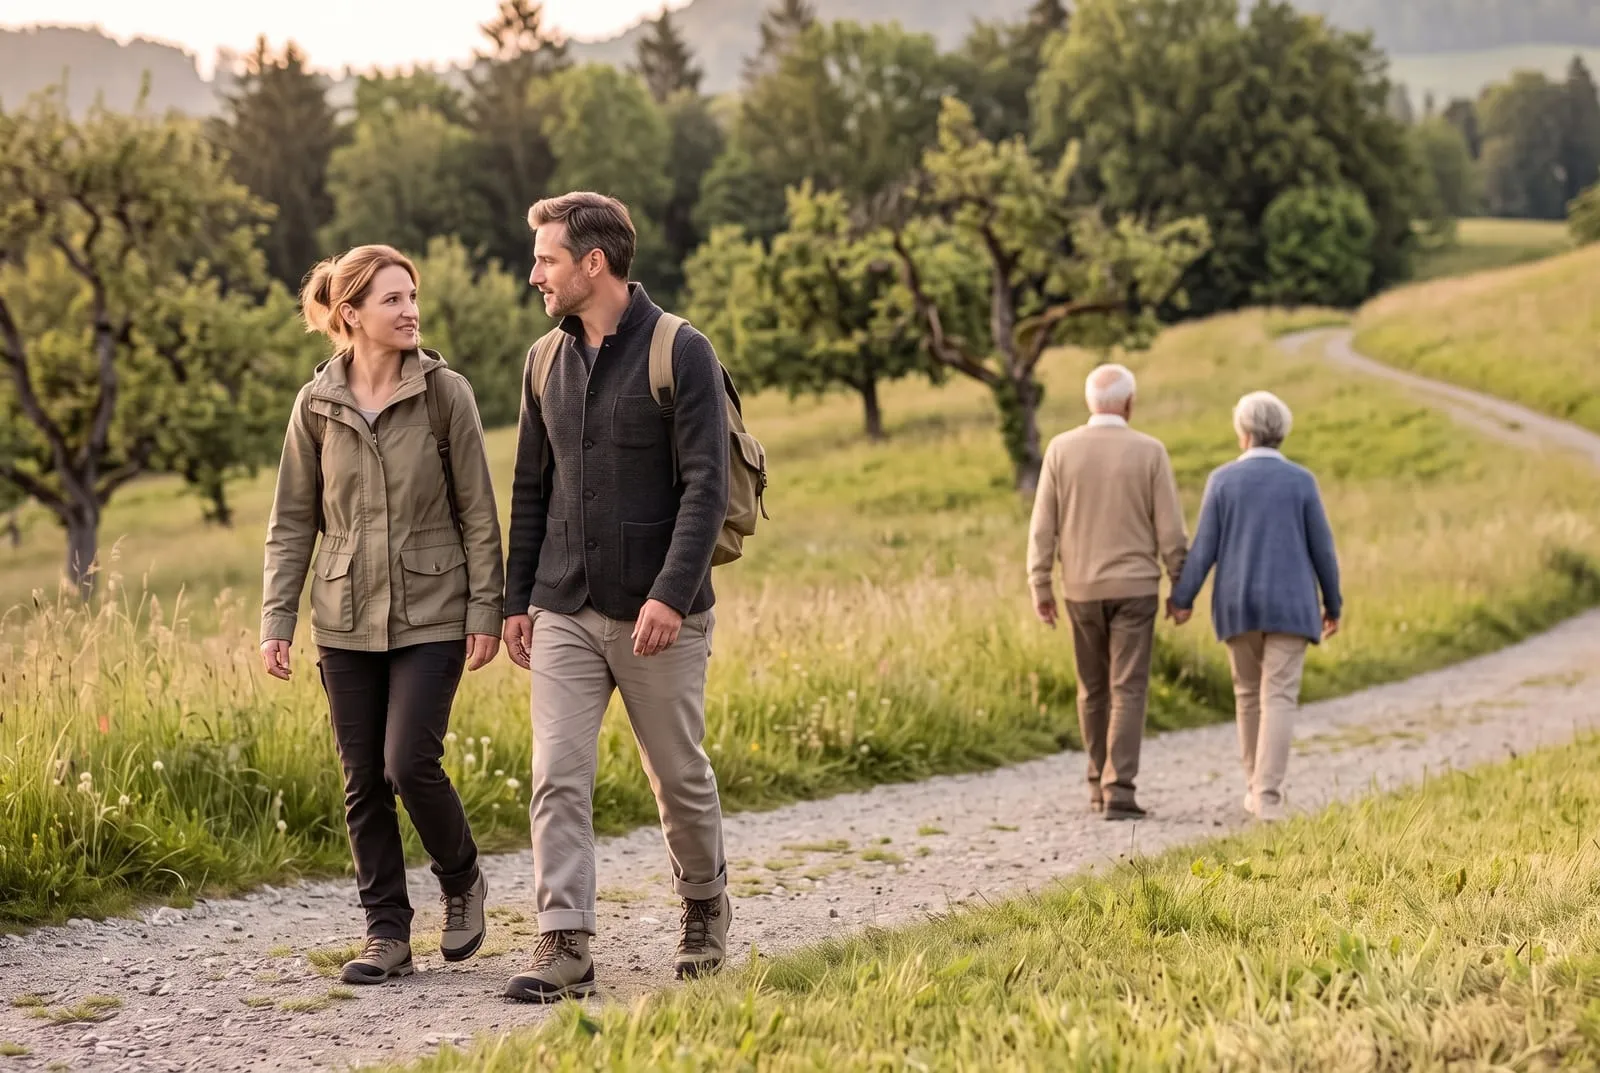
Saving on autopilot, for a life not yet defined
- You want to feel financially secure, but "how much is enough?" stays vague.
- Saving and investing run on autopilot, with no clear link to the life you want.
- You're unsure how to balance living well now with providing for later.
- Retirement feels distant, or uncomfortably close, and you want clarity rather than anxiety.
- You're ready to align your finances with the life you actually want to lead.
Four stages. A system that holds when motivation doesn't.
The logic well-run organisations use for what matters, sized for one person, couple or family. Structured conversations, work between sessions on both sides, and a system you run.
A written System Blueprint: the scope and objectives of the area, the few routines that carry it, the review rhythm, and the principles behind them. Then the system itself, set up and run through its first cycles.
Usually all four sprints in order, each a fixed scope of one to three 90-minute working sessions, online, plus work in between on both sides. You buy the result, not hours. A check-in within 30 days is included.
End a sprint at any point and pay only for what was done by then, never the full fee without the deliverable. Half the fee is invoiced on confirmation and half with the deliverable; if a sprint ends earlier, the difference is settled as a refund or as a final invoice.
Everything stays between us. No third parties, no exceptions unless you ask or the law requires it.
The number changes. The life shouldn't.
Because "enough" depends on the life you want to lead, and a rule of thumb doesn't know it. Without that picture, saving runs on autopilot and every market move feels personal. A management system fixes that: what the money is for, the numbers that actually matter, and a review rhythm that turns surprises into adjustments. The investment decisions stay with you and whoever advises you on them. What we build is the structure that holds them.
An advisor, not a coach
PhD, Global Executive MBA. I have advised organisations and leaders on high-stakes choices for over a dozen years and now bring the same methods to individuals at career and life crossroads. Structure, proven methods, and empathy. No hidden agenda, no upsell.
More about meQuestions people ask
Can you help with financial decisions?
With the structure, yes: a budget, the financial side of a life system, or what different scenarios would mean for you. What I do not do is regulated financial advice. No product recommendations, no investment picks, no commissions from anyone.
Can someone else take part: my partner, a parent, a co-founder?
Yes, when the question is theirs too. We agree at the start which sessions we hold together and which you take alone, because some thinking is easier without an audience. What is said in an individual session stays there, and the result is written for the person whose situation it is.
Nobody knows how this plays out. What can a plan do?
Not predict, and it does not try. What it does is name the few developments that could actually reach you, set out what you would do in each case, and fix the signals that tell you which case you are in. Then the plan has review points instead of a shelf life. When the world moves, you adjust a decision you already thought through rather than starting from the headline.
Will I depend on you to keep the system running?
No, and the last stage is designed to make sure of it. The system lives in your own tools, with a short operating manual, and the check-ins thin out as it becomes simply how things work. If life changes and the system needs a redesign, you know how to do it, or you come back for one sprint. What you will not need is a standing appointment.
The Live the System sprintTalk it through before you decide anything
30 minutes, online. We look at your situation, I tell you honestly whether structured advisory would help, and you decide. No preparation needed.
Dr. Dominik LangerYou are writing to me directly. I reply personally.